
Business loans decided locally, not by algorithms
Getting a business loan should be straightforward and decided locally - by those who understand seasonal cycles or your need to invest in major real estate and equipment to scale your business.
 Flat fees
- Pay-as-you-go transparency
 Trusted by 65K+ members
Balance required
$0
Monthly fee
$5
Flat fee
Lending options when your capital needs aren't one-size-fits-all.
True hospitality and care means designing financial tools that actively protect your profit margins. Here's how holding an automated US Dollar ledger from YNCU changes your day-to-day operations.
 Fluid
Lines of Credit
 Ideal for everyday cash flow-balancing daily operational expenses, covering seasonal payroll cycles, or funding upfront inventory purchases.
- Pay-for-what-you-use to keep costs low by paying interest only on the exact amount you draw, not your total limit.
- Apply once, and reuse anytime. Draw funds whenever you need them, repay as your invoices clear, and watch your credit automatically become available again without any secondary credit checks.
 Structured
Business Term Loans
- Ideal for major investments like purchasing specialized machinery, expanding your fleet, upgrading your office, or consolidating high-interest debt.
- Predictable interest structure as interest is calculated as a steady percentage of the full lump-sum advanced directly to your account.
- Simple book keeping: Choose between fixed or variable rates with structured amortization, giving you predictable monthly payments and financial forecasts.
 Fast
Farm and agriculture
- Keep cash flow moving through the seasons, with financing for planting, harvest, operating costs and the gaps in between.
- Finance the equipment and assets your farm needs, from tractors and vehicles to livestock, infrastructure and other major investments.
- Borrow with people who understand agriculture, with flexible financing built around the realities, timing and long-term plans of your operation.
Compare loans to fit your business
Compare flexible lines of credit, structured term loans at a glance. Have a unique project in mind or need commercial real estate options? Contact us or apply for a YNCU business loan today.
| Features | Commercial loan | Line of credit |
|---|---|---|
| Primary intent | One-time investment | Daily cash flow fexibility |
| Funding | Lump-sum injection | Revolving on-demand |
| Interest applied | Entire loan amount | Only on drawn balance |
| Repayment | Structured payments | Flexible, minimal interest |
YNCU's local lending advantage
At a lot of banks your loan application is often reduced to an automated score. Our local specialists actually know your market and truly understand your business goals. Here are some advantages of working with us:
Customized payments
Tailored to your business cycles, we can structure payment timelines around your business's natural cash flow cycles, offering sophisticated, flexible terms tailored specifically for agricultural and seasonal operations.
More capital options
We have more capital access options like streamlining Canada Small Business Financing Program (CSBFP) applications, helping you get bigger credit limits and lower collateral requirements.
Quick approvals
We have streamlined local infrastructure to replace weeks of bureaucratic oversight to deliver loans faster to match the speed of your market opportunities.
Should I get a loan or line of credit?
Commonly asked questions
An unsecured commercial or business line of credit relies on your business's credit rating and personal guarantees, typically carrying a slightly higher interest rate. A secured line of credit leverages tangible business assets—such as your accounts receivable ledger, equipment inventory, or commercial real estate—to unlock significantly higher borrowing limits at our lowest available interest rates.
Yes. Unlike rigid commercial finance structures that lock you into inflexible prepayment penalties, our conventional business loans are built with flexible open options, allowing you to make additional principal payments or clear the balance entirely whenever your cash flow allows.
Generally speaking, for standard small business loans under $100,000, credit decisions can typically be generated within a few business days once your complete document package is submitted. Larger, more complex commercial property development or construction facilities scale depending on third-party appraisal timelines.
Eligible non-registered business deposits at YNCU are insured up to $250,000 per category through Ontario’s Financial Services Regulatory Authority (FSRA). In contrast, standard non-registered deposits at Canada’s Big 5 banks are insured up to $100,000 through the Canada Deposit Insurance Corporation (CDIC), giving YNCU business members 2.5x higher deposit protection limits on their operating cash reserves.
Yes. YNCU online business banking supports multi-user permissions and dual signature approvals. Business owners can assign customized access levels to employees or accountants—allowing team members to draft electronic payments, direct deposits, or wire transfers while requiring a second authorized signer to approve them prior to release.
Manage your business loans anytime, anywhere
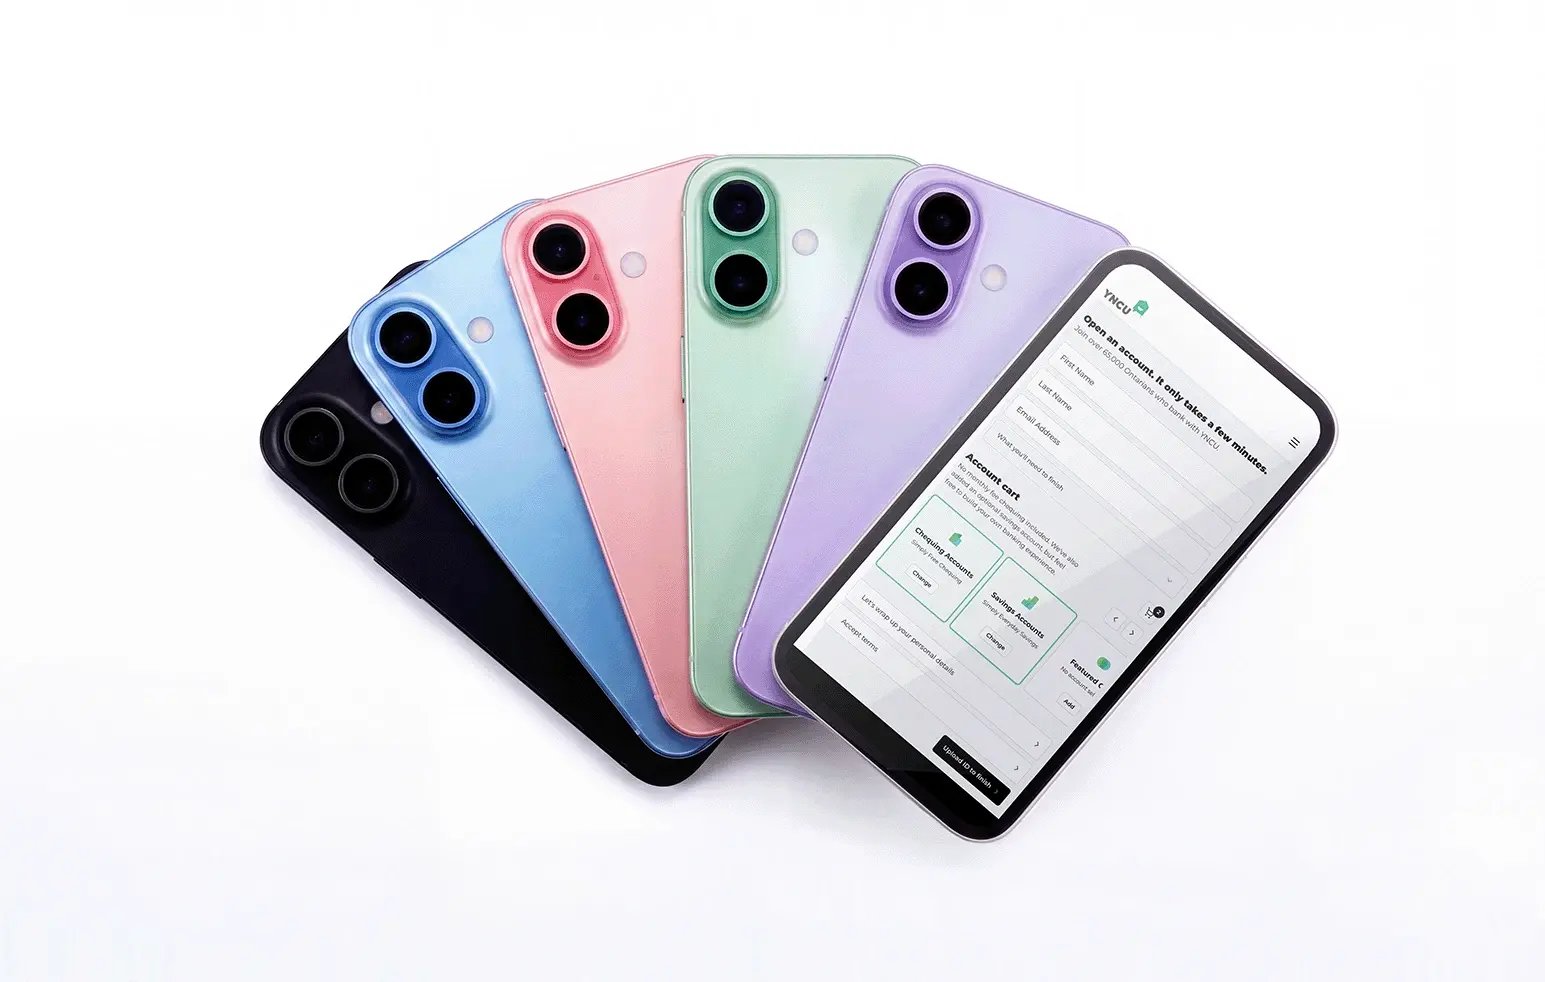
Stay on top of your financing from your phone. Get the YNCU mobile app to track balances, make payments, and manage your cash.
Download our mobile banking app.
Business related stories and articles
Borrow
August 3, 2026 | Rana Simpson | 6 min Read
Student financial aid in Canada: Grants, loans and tips
1 The YNCU New Client Payroll Offer (the “Offer”) is available to new Clients who(se): (a) Client Number was created between May 1, 2024 and October 31, 2026; (b) open a YNCU Chequing Account as the Primary Account Holder within 60 days of the date their Client Number was created; and (c) set up payroll direct deposits within 60 days of the date their Chequing Account was opened. A cash Bonus of $250 will be paid to the new Client’s YNCU Chequing Account if the Client switches their eligible automated and recurring payroll direct deposits to their new YNCU Chequing Account, provided that: (i) they deposit the full amount of their payroll direct deposits; (ii) payroll direct deposits total a minimum of $200 on a monthly basis; (iii) the first eligible payroll direct deposit is received in their Account within 60 days of successfully opening the Chequing Account; and (iv) their subsequent eligible payroll direct deposits continue for at least 2 consecutive months. The Bonus will be paid to the Client’s YNCU Chequing Account in the subsequent month following the satisfaction of the Offer conditions. Offer can’t be combined with any other Chequing cash bonus Offers and is limited to one (1) Bonus per Client. By accepting any Offer, you agree to the terms and conditions of this Offer. Full Offer Terms and Conditions, including definitions of any capitalized terms, are available here. Offer may be changed, extended or cancelled without notice.
† Savings Account, Chequing Account, and GIC interest rates expressed on this website are annual interest rates and are current as of today's date. Interest rates are subject to change without notice. Interest is calculated daily and paid monthly on our Savings and Chequing Accounts. GIC terms of one year or longer have interest calculated on the basis of 365/366 days and compounded and/or paid annually. GIC terms of less than one year have interest calculated on the basis of 365/366 and paid at maturity.
6 YNCU will waive the ABM Withdrawal Fee and Global ATM Alliance members will waive any surcharge fees for withdrawal transactions performed at a Scotiabank or Global ATM Alliance machine with your YNCU Client Card. Some exclusions apply; see our Fee Schedule for details. The current Fee Schedule can be found at yncu.ca/feeschedule.
*Trademark of Visa International Service Association and used under license
‡Pay no fees for everyday Chequing transactions. For non-standard transactions, a fee may apply.
7Full terms and conditions are outlined in the Account Terms and Client Card Cardholder Agreement available to you on our website at yncu.ca.
Interac and Interac e-Transfer are registered trademarks of Interac Corp, used under licence.
Cheque-In® is a registered trademark of YNCU Bank.
® ApplePay is a registered trademark of Apple Inc., registered in the U.S. and other countries.
™ Google Pay is a trademark of Google LLC.
® Samsung Pay is a registered trademark of Samsung Electronics Co., Ltd.
3 Some conditions may apply. Service is subject to availability and successful digital verification.
4 As of Mar 10, 2026 there were 49.9K reviews with an average rating of 4.5 from the Google Play Store and 77K reviews with an average rating of 4.7 from the App Store.
® App Store is a registered trademark of Apple Inc., registered in the U.S. and other countries.
™ Google Play is a trademark of Google LLC.